Moneycat loan review is a critical topic for Filipino borrowers searching for a reliable financial lifeline without falling into a “debt trap.”
As the digital lending landscape in the Philippines grows, understanding whether an app is a legitimate partner or a source of harassment is essential for your financial safety.
This guide provides an in-depth look at Moneycat’s operations, legal standing, and user experiences to help you make an informed decision.
Is Moneycat SEC Registered in the Philippines?

One of the first things any borrower should check is the legal status of a lending platform with the Securities and Exchange Commission (SEC).
Moneycat Financing Inc. is a registered entity in the Philippines, holding SEC Registration Number CS201953073.
The company operates under Certificate of Authority (CA) Number 1254, which confirms its license to provide lending services.
Being a sec registered loan app means the company is required to follow the Lending Company Regulation Act and the Truth in Lending Act.
However, registration does not automatically mean every user experience is perfect, as regulatory compliance covers interest rate disclosures and fair collection practices.
You should always verify the current status of any sec registered online lending app before submitting your personal data.
Moneycat Loan App Features and Requirements
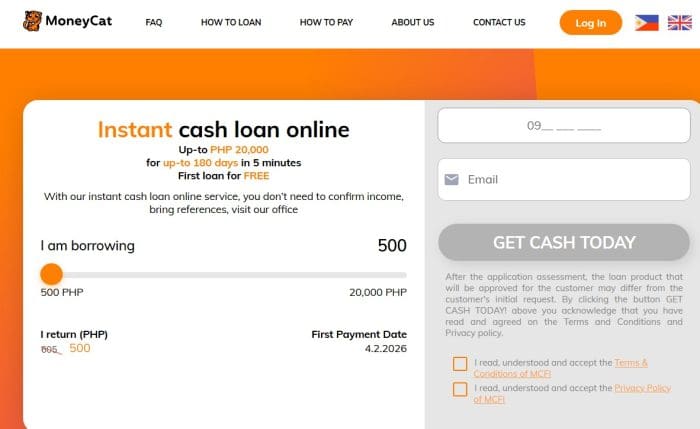
Quick summary Moneycat Loan App Features
| Feature | Details |
| App Name | MoneyCat Philippines |
| Corporate Name | MoneyCat Financing Inc. |
| SEC Registration No. | CS201953073 |
| Certificate of Authority (CA) | 1254 |
| Loan Amount | 500 PHP – 20,000 PHP |
| Loan Term | 3 months to 6 months |
| Monthly Interest Rate | 11.9% per month |
| Maximum APR | 145% |
| Requirements | 1 Valid ID, Filipino citizen, Age 22-60 |
| Disbursement Channels | GCash, Maya, Bank Transfer, LBC |
| Repayment Channels | 7-Eleven, GCash, Maya, Bayad Center |
The Moneycat loan app is designed for speed, targeting Filipinos who need quick cash for emergencies or bills.
To qualify for a loan, you must be a Filipino citizen currently residing in the Philippines.
The age requirement typically ranges from 22 to 60 years old, ensuring the borrower has a stable source of income.
You will need at least one valid government-issued ID, such as a UMID, SSS, Passport, or Driver’s License.
Unlike traditional banks, Moneycat does not usually require collateral or complex financial statements for its basic loan products.
The application is entirely online, which is convenient but requires a stable internet connection and a smartphone.
Analysis of Moneycat Loan Interest Rate and Fees
Understanding the Moneycat loan interest rate is vital to avoid surprises during your repayment schedule.
For first-time borrowers, Moneycat often offers a “0% interest” promotion for a very short term, usually 7 to 10 days.
Under normal terms, the interest rate is approximately 11.9% per month, with a maximum Annual Percentage Rate (APR) of 145%.
The Moneycat lending app offers loan amounts ranging from 500 PHP to 20,000 PHP with terms of 3 to 6 months.
While this sounds attractive, you must look closely at the processing fees that are often deducted from the principal amount before disbursement.
If you borrow 5,000 PHP, you might only receive 4,200 PHP in your GCash or bank account due to upfront service fees.
Always read the disclosure statement provided in the app before clicking “Accept” to see the total cost of credit.
The Moneycat Process: From Application to Disbursement
The Moneycat loan app prides itself on a “5-minute application” process that appeals to the fast-paced life in Manila and Cebu.
First, you download the app and register using your mobile number.
Next, you fill out the digital form with your personal details, employment information, and emergency contacts.
You will then be asked to take a selfie and upload a clear photo of your valid ID.
The system uses automated credit scoring to determine your eligibility and loan limit.
If approved, the funds are typically sent to your nominated bank account, GCash, or Maya within 24 hours.
Why Was My Moneycat Loan Rejected?
Many users ask why their application was rejected despite meeting the basic age and ID requirements.
The most common reason is “Contact Access” or “Permissions” issues where the app cannot verify your digital footprint.
Inconsistent information between your ID and the application form can also lead to an immediate denial.
If you have existing unpaid loans with other OLA (Online Lending Apps), the credit scoring system may flag you as a high-risk borrower.
Sometimes, simply having a low-quality selfie or an expired ID is enough for the automated system to decline the request.
You can usually re-apply after 30 days if your initial attempt was unsuccessful.
Moneycat Harassment Review: Addressing User Concerns
A major part of any Moneycat harassment review involves the collection methods used when a borrower fails to pay on time.
Many Moneycat complaints on social media center around “debt shaming” or aggressive phone calls to emergency contacts.
Some users report that the app’s collection agents call their workplace or send threatening text messages.
It is important to know that the National Privacy Commission (NPC) prohibits “contact harvesting” for the purpose of harassment.
If you experience abusive behavior, you can file a formal complaint with the SEC’s Enforcement and Investor Protection Department.
While the company is legal, the behavior of third-party collection agencies remains a point of contention for many Filipino borrowers.
Moneycat Review Complaints and Reddit Feedback
Looking at a Moneycat review complaints thread on reddit provides a raw perspective on the user experience.
Redditors often warn about the “snowball effect” of high interest rates if you only pay the minimum amount.
Common Moneycat complaints include technical glitches where a payment was made via 7-Eleven but not reflected in the app.
Users on Reddit often suggest comparing different apps to find the one with the least aggressive collection tactics.
Many recommend using Moneycat only for absolute emergencies and paying it off as soon as your salary arrives.
The consensus among the community is that while the app provides fast cash, the cost of convenience is very high.
You may also compare other verified loan apps available in the Philippines.
Is Moneycat Legit and Safe to Use?
The question “Is Moneycat legit?” has a two-part answer: legally yes, but operationally, it requires caution.
It is a legitimate business registered with the SEC, which provides a layer of protection compared to “underground” lenders.
However, “safe” depends on your ability to manage high-interest debt and handle potential collection pressure.
If you pay on time, you will likely have a smooth experience and build a higher credit limit.
If you default, you risk damage to your privacy and a significant increase in total debt due to late penalties.
Always ensure you are using the official website or the official Google Play Store link to avoid phishing scams.
FAQs
What is the Moneycat contact number for customer service?
You can reach Moneycat through their official hotline at 09171527089 / 09171526738 or email: [email protected] for concerns regarding your account.
Does Moneycat report to the Credit Information Corporation (CIC)?
Yes, as a regulated lending company, they are mandated to report borrower data, which can affect your credit score.
Can I pay my Moneycat loan using GCash?
Yes, GCash is a primary payment partner; you can find Moneycat under the “Bills” section of the GCash app.
What happens if I cannot pay my loan on time?
Late payment fees will be applied daily, and your account will be endorsed to a collection agency for recovery.
How can I delete my Moneycat account?
You must settle all outstanding balances first before requesting account deletion through their customer support email.
Is Moneycat available for iOS users?
Moneycat is primarily optimized for Android, but check the Apple App Store for the most recent version available for iPhone.
Final Verdict on Moneycat Philippines
The Moneycat loan review concludes that this app is a functional tool for those who need immediate liquidity.
Its legal loan app status provides peace of mind that you are dealing with a recognized entity in the Philippines.
However, the high interest rates and reports of aggressive collection tactics mean you should use it with a clear repayment plan.
Always prioritize your privacy by reviewing the app permissions before installation.
Managing your finances wisely is the best way to avoid the stress of “harassment” and late fees.
⚠️ Financial Disclosure: This app is reviewed for informational purposes. Before applying, always verify its SEC Registration and Certificate of Authority. Be mindful of the Effective Interest Rate (EIR), Processing fees, and Service fees. Borrow responsibly to avoid high penalties and debt traps.


My application was rejected yesterday without any clear reason. I submitted my UMID and a clear selfie. I am a regular employee with a stable salary. Is there a specific contact number or email where I can appeal? I really need the funds for my child’s tuition fee this week.
I’m sorry to hear about the rejection, Catriona. Common reasons include “digital footprint” issues or existing OLA records. You can try reaching their hotline at 09171527089 / 09171526738 or email: [email protected]. Alternatively, look for other sec registered lending company options on our site that might have different credit scoring criteria.