PesoGo review searches have surged as more Filipinos look for quick cash solutions.
But with the rise of “loan sharks” in app form, verifying legitimacy is the first step toward financial safety.
Whether you are facing an emergency or just need a small bridge loan, knowing if PesoGo is a legal loan app with a valid Certificate of Authority is non-negotiable before you hit the “apply” button.
What is PesoGo Lending App?
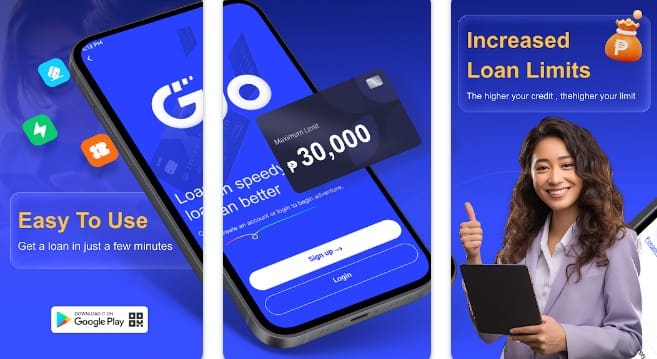
PesoGo is a mobile lending platform designed to provide fast, unsecured personal loans to Filipino citizens.
In a country where traditional bank requirements can be a barrier, PesoGo offers a digital-first approach.
It allows users to apply using only their smartphones and a single valid government ID.
The app is operated by Dolphin Lending Investor, Inc.
This corporate entity positions itself as a partner for those needing “salary stretch” funds.
While the speed of GCash disbursement is its primary selling point, the app has been the subject of various PesoGo complaints.
These complaints on social media often regard its collection methods and high service fees.
PesoGo App Features & Summary 2026
To give you a quick overview of what to expect when using this platform, here is a summary of its operational parameters:
| Feature | Details for 2026 |
| Operating Company | Dolphin Lending Investor, Inc. |
| SEC Registration No. | CS201911897 |
| Certificate of Authority (CA) | No. 3037 |
| Loan Amount Range | ₱1,000 – ₱30,000 |
| Loan Term | 185 Days – 210 Days |
| Disbursement Channels | GCash, Maya, Bank Transfer |
| Target Market | Filipino Citizens (18-60 years old) |
Is PesoGo Legit and SEC Registered?

Yes, PesoGo is a legitimate entity.
Unlike many “fly-by-night” apps that lack proper documentation, PesoGo is operated by Dolphin Lending Investor, Inc.
It holds SEC Registration No. CS201911897 and Certificate of Authority No. 3037.
Being a sec registered online lending app means they are legally permitted by the Securities and Exchange Commission to engage in lending activities.
However, being “legit” in the eyes of the law does not always mean a “stress-free” experience for the borrower.
Users must still adhere strictly to the repayment schedule to avoid high-pressure tactics.
These tactics are often mentioned in a PesoGo harassment review.
Understanding the PesoGo Loan Interest Rate
While the app offers a relatively long loan term (185 to 210 days), the cost of borrowing remains high.
This is due to the combination of interest and service fees.
Sample Calculation
If you apply for a loan of ₱10,000:
Principal Amount: ₱10,000.
Service Fee (Estimated 10%): ₱1,000.
Net Amount Received: ₱9,000.
Interest (e.g., 0.05% per day for 185 days): ₱925.
Total Repayment: ₱10,925.
Effective Daily Rate: Varies based on the credit tier.
Always check the “Disclosure Statement” before e-signing the contract.
The PesoGo lending app is required by the Truth in Lending Act to show the full breakdown of fees.
Detailed PesoGo Requirements
To ensure a high approval rate, you must meet the following PesoGo requirements:
-
Valid Government ID: UMID, SSS, Driver’s License, or Passport are preferred.
-
Proof of Residency: You must be living in the Philippines.
-
Age Limit: 18 to 60 years old.
-
Stable Mobile Connection: For OTP and verification calls to your contact number.
-
Employment Info: While no payslip is usually required, you must provide your employer’s name.
How to Apply PesoGo: Step-by-Step
-
Download the App: Available via the official website or Google Play Store.
-
Register: Use your active mobile number.
-
Fill out Information: Provide your Barangay details, work info, and references.
-
Identity Verification: Take a selfie and a photo of your Valid ID.
-
Wait for Approval: This can take anywhere from 5 minutes to 24 hours.
The PesoGo Harassment Review: What to Watch For
Despite its legal status, the app has faced criticism in the Reddit and Facebook communities.
Most PesoGo review complaints revolve around the “pre-collection” phase.
Agents may start calling 1-2 days before the actual due date.
Like most online lending apps (OLA), PesoGo requires permission to access your contacts during installation.
Some users report that if they become unreachable, the app agents may contact their references.
While not all agents are abusive, some borrowers have reported aggressive language during the collection process.
If you believe your rights under the National Privacy Commission (NPC) have been violated, document all communication.
Report them directly to the SEC Enforcement and Investor Protection Department.
Why People Choose PesoGo (Pros)
-
Accessibility: It is much easier to get approved here than in a traditional bank.
-
High Loan Limit: The ability to reach ₱30,000 is higher than many competitors.
-
Longer Terms: The 185-day minimum term is a significant advantage over 7-day apps.
-
SEC Compliance: Knowing they are a sec registered lending company provides legal recourse.
Common PesoGo Complaints (Cons)
-
High Service Fees: The “deducted upfront” fees mean you get less cash than you borrowed.
-
Aggressive Notifications: The app may send numerous SMS as the due date approaches.
-
Technical Glitches: Some users report delays in updating their payment status on the dashboard.
How to Contact PesoGo (Official Channels)
If you have issues with your account or payment, use the following:
Official Website: https://pesogo.ph/ (Check the app for the most current link).
CS Contact Number: [email protected] (Usually found within the “Help Center” section of the app).
Physical Office: #367 Torre Venezia Suites 170 TimogAvenue cor.Scout Santiago St, Quezon City 1103 (Dolphin Lending Investor, Inc. is required to have a registered office in the Philippines).
PesoGo Final Scorecard 2026
To help you make an informed decision, we evaluated PesoGo based on several core factors:
| Evaluation Criteria | Score | Key Takeaway |
| Legitimacy & SEC | 5.0 / 5 | Fully registered under Dolphin Lending Investor, Inc. |
| Loan Amount | 4.0 / 5 | High limit up to ₱30,000 for repeat borrowers. |
| Repayment Term | 4.5 / 5 | 185–210 days is much longer than the 7-day average. |
| Interest & Fees | 3.0 / 5 | APR and service fees remain relatively high. |
| User Experience | 3.5 / 5 | Fast approval but sensitive to collection reminders. |
| Data Privacy | 3.0 / 5 | Requires extensive phone permissions for approval. |
App Trust Score: 3.8 / 5
PesoGo is a solid option because of its verified SEC credentials and generous repayment window.
However, its final grade is tempered by high service fees and a collection style that many users find overly persistent.
If you need immediate cash and can commit to on-time payments, PesoGo is a legitimate and functional choice for Filipinos in 2026.
FAQ: Frequently Asked Questions
Is PesoGo a legal loan app in 2026?
Yes, it is operated by Dolphin Lending Investor, Inc., which holds a valid Certificate of Authority (No. 3037).
It is a legally recognized entity by the SEC.
Can PesoGo access my Facebook contacts?
If you grant the app permissions to your contacts or link your social media, they may have access to that data.
Always review the “Privacy Policy” before agreeing to permissions.
What happens if I don’t pay my PesoGo loan?
Your account will accrue late fees and interest.
Your credit score with the Credit Information Corporation (CIC) may be negatively affected.
Furthermore, you may experience persistent collection efforts from their agents.
Is the PesoGo loan amount really up to ₱30,000?
For first-time borrowers, the limit is usually low, around ₱2,000 to ₱4,000.
You must demonstrate “good payer” behavior to unlock the ₱30,000 maximum limit.
How do I stop harassment from loan apps?
If you are being harassed, file a complaint with the SEC and the NPC.
You can also report the app to the Google Play Store for violating their policy regarding abusive collection.
Final Verdict: Should You Use PesoGo?
PesoGo is a viable option for those who are unbanked but need immediate liquidity.
Because it is a sec registered online lending app, it is safer than “underground” lenders.
However, the high interest and potential for aggressive collection means it should only be used as a last resort.
Always borrow what you can afford to pay back within the loan term to avoid the stress of debt.
⚠️ Financial Disclosure: This app is reviewed for informational purposes. Before applying, always verify its SEC Registration and Certificate of Authority. Be mindful of the Effective Interest Rate (EIR), Processing fees, and Service fees. Borrow responsibly to avoid high penalties and debt traps.


I experienced a bit of a shock when I saw the actual amount credited to my GCash. While PesoGo is definitely legit and SEC registered, the upfront service fees are quite steep. I received much less than the ₱5,000 I applied for, although the 185-day term helps with repayment.
Thank you for sharing your experience, Juan. You’ve highlighted the most common trade-off: higher fees in exchange for longer terms and fast approval. It is always vital to check the Net Proceeds before e-signing.
I tried applying yesterday using my UMID card and got approved in less than 30 minutes! The interface is smooth and the requirements are very minimal compared to bank loans. I just hope the technical glitches others mentioned about payment updates won’t happen when I settle my balance.
That is a very fast turnaround, Althea! To avoid the glitches you mentioned, make sure to keep a screenshot of your payment receipt from GCash/Maya. This serves as your “solid proof” if the app dashboard fails to update instantly.
Is the ₱30,000 limit actually reachable? I am currently on my second loan with them and my limit only increased by ₱1,000. I’ve been a good payer but the jump to the maximum amount seems very slow. Is there a specific trick to unlock the higher credit limit?
Hi Ricardo! In my research, reaching the ₱30,000 ceiling usually takes 4-5 successful loan cycles with zero delays. There’s no “trick” other than consistency. However, always weigh if the higher limit is worth the recurring service fees!