Blue Peso loan review is the most essential guide for Filipinos looking for quick cash solutions while navigating the complex world of online lending in 2026.
With the rise of various financial apps, understanding which ones are legitimate and which ones might cause personal stress is vital for every borrower.
This article provides an in-depth look at Blue Peso, its official registration, and whether the rumors of harassment are backed by user experience.
Is Blue Peso Legit and SEC Registered in the Philippines?
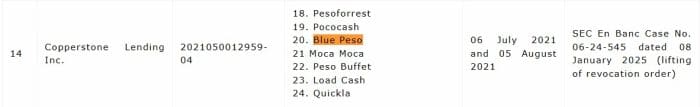
The legitimacy of any lending platform in the Philippines starts with its SEC status.
Blue Peso is operated by Copperstone Lending Inc., a company that has undergone the necessary legal hurdles to operate.
As of 2026, Copperstone Lending Inc. holds SEC Registration No. 2021050012959-04.
More importantly, they possess a Certificate of Authority (CA) No. 3454, which specifically allows them to operate as a lending company.
Having these credentials makes it a legal loan app compared to the “underground” or “pirate” apps that operate without any government oversight.
However, being a sec registered online lending app does not mean borrowers should let their guard down regarding interest rates.
Verification is key, and users are encouraged to check the SEC’s official list of revoked or suspended lending companies regularly.
Searching for Blue Peso legit often leads to mixed results because legality and “user friendliness” are two different things in the OLA industry.
Blue Peso Loan Product Details and Requirements
To ensure a smooth application, you must understand the specific Blue Peso requirements and the financial products they offer.
The platform is designed for mobile users who need a paperless experience without visiting a physical bank branch.
The Blue Peso loan app is available on major app stores and requires a stable internet connection for the biometric verification step.
Eligibility Criteria
-
Must be a Filipino citizen currently residing in the Philippines.
-
Age must be between 18 and 60 years old.
-
Must have at least one valid government ID (PhilSys, UMID, SSS, or Driver’s License).
-
A verifiable source of income or employment.
-
An active mobile number and a personal e-wallet or bank account for disbursement.
Blue Peso Loan Interest Rate and Terms
One of the most attractive features for 2026 is the extended loan term of 91 to 180 days.
This is a significant improvement over many other apps that only offer 7 or 14-day windows.
The Blue Peso loan interest rate is competitive within the OLA market, but users must watch out for the service fees.
If you borrow PHP 10,000 for 91 days, your daily interest rate might be around 0.1% to 1%, depending on your credit profile.
Total Interest = Principal x Daily Rate x Number of Days.
If the daily rate is 0.1%, then: 10,000 x 0.001 x 91 = 910 PHP in interest.
Always subtract the “Administrative Fee” from the principal to see the actual amount you will receive in your GCash or bank account.
Step-by-Step Blue Peso Application Process
The process of getting your first loan is streamlined to take less than 15 minutes if you have your documents ready.
First, download and install the Blue Peso lending app from a trusted source.
Second, enter your mobile number and verify it using the One-Time Password (OTP) sent to your device.
Third, complete the “Identity Verification” by taking a clear photo of your government ID.
Fourth, perform the “Liveness Check” where you will be asked to blink or turn your head in front of the camera.
Fifth, fill in your personal, professional, and emergency contact information.
Finally, select your desired loan amount and term, then submit the application for real-time credit scoring.
The system will then evaluate your data and provide an approval or reject status within minutes.
Pros and Cons of Using Blue Peso
Every financial tool has its trade-offs, and the Blue Peso lending app is no exception. Understanding these pros and cons will help you decide if this app fits your current financial situation.
Advantages (Pros)
-
High Approval Rate: Even those with a “reject” history in traditional banks often get approved here.
-
Fast Disbursement: Funds are usually sent to your GCash or bank account within minutes of approval.
-
Extended Terms: Unlike 7-day apps, Blue Peso offers terms ranging from 91 to 180 days.
-
Fully Digital: No need for physical paperwork or office visits; everything is done on your phone.
Disadvantages (Cons)
-
High Service Fees: The amount you receive is often lower than the amount you applied for due to upfront deductions.
-
Privacy Permissions: The app requires access to your contacts, which is a major concern for many.
-
Aggressive Reminders: Some users report receiving multiple calls and texts days before the due date.
-
Penalty Rates: Late payments result in heavy daily fines that can quickly accumulate.
Why Do Borrowers Get a Blue Peso Reject Status?
It is frustrating to be rejected when you are in an emergency, but the system has strict risk parameters.
A common reason for rejection is an unclear photo of your ID, which prevents the AI from verifying your identity.
Another factor is an “Inconsistent Contact List,” where the references provided do not match the digital footprint.
If you have multiple outstanding loans with other apps, the Blue Peso loan app might flag you for “over-indebtedness.”
To improve your chances, ensure you are using your own smartphone and that your GPS location is turned on during the application.
Always double-check that your bank account name matches the name on your government ID exactly.
Blue Peso Harassment Review: Understanding Collection Practices
The term Blue Peso harassment review often appears in online forums and consumer protection groups.
While Copperstone Lending Inc. is regulated, some third-party collection agencies may use aggressive tactics.
Common Blue Peso complaints include frequent automated calls and SMS reminders starting days before the actual due date.
Some users on reddit have reported that collectors may call their emergency contacts if the borrower becomes unreachable.
It is important to know that the SEC and the National Privacy Commission (NPC) strictly prohibit “debt shaming” or unauthorized access to contact lists.
If you experience Blue Peso review complaints related to threats or profanity, you should document every interaction.
Keep screenshots of texts and record phone calls as evidence for a formal complaint to the authorities.
Blue Peso Contact Number and Official Website
Finding a reliable Blue Peso contact number is the best way to settle disputes or request payment extensions.
Scammers often post fake customer service numbers in the comments section of social media posts.
You should only use the contact details provided within the official app or the website of Copperstone Lending Inc.
If you cannot reach them by phone, sending a formal email is the next best step for a paper trail.
Never share your OTP or login credentials with anyone claiming to be a “Blue Peso Agent.”
Official agents will never ask for “Advanced Processing Fees” via personal GCash accounts.
| Feature | Blue Peso Specification 2026 |
| Operator | Copperstone Lending Inc. |
| SEC Registration | 2021050012959-04 |
| Certificate of Authority | 3454 |
| Loan Term | 91 – 180 Days |
| Minimum Loan | PHP 2,000 |
| Maximum Loan | PHP 20,000 (Subject to Credit) |
| Disbursement | GCash, Maya, Bank Transfer |
Managing Your Debt and Avoiding the Debt Trap
A Blue Peso loan review would be incomplete without discussing financial responsibility.
Short-term loans are convenient but can become a “debt trap” if you keep “rolling over” the principal.
Before clicking “Apply,” calculate if your next salary can cover the total repayment without sacrificing your daily needs.
If you find yourself unable to pay, contact the Blue Peso lending app support immediately to negotiate a payment plan.
Ignoring the debt will only lead to higher penalties and more frequent collection calls.
Remember, your credit history with these apps is now being reported to centralized credit bureaus in the Philippines.
Blue Peso Rating Section
Based on thousands of user interactions across the Google Play Store and social media platforms like Reddit, the Blue Peso review complaints are balanced by those who successfully navigated the repayment cycle. As of 2026, the app maintains an average user rating of 3.8 out of 5.0 stars.
-
Speed of Process: 4.5 / 5.0 (Extremely fast automated approval system).
-
Interest & Fees: 2.5 / 5.0 (High upfront service fees and daily interest rates).
-
Customer Service: 3.0 / 5.0 (Responsive, but often aggressive during collection cycles).
-
App Stability: 4.0 / 5.0 (The interface is user-friendly and supports most Android devices).
Frequently Asked Questions
Is Blue Peso safe for my personal data?
They claim to use encryption, but like all OLAs, they require access to your camera and location for verification.
Always read the “Privacy Policy” to see how they handle your contact list and photo gallery.
Can I pay my loan via GCash or 7-Eleven?
Yes, Blue Peso supports multiple payment channels including GCash, Maya, and over-the-counter partners like 7-Eleven (CLiQQ).
Always save your electronic receipt until the app reflects that your loan is fully paid.
What should I do if I am being harassed?
First, do not panic and do not delete the threatening messages.
Second, contact the company’s compliance officer to report the specific collector.
Third, if the behavior persists, file a complaint with the SEC’s Corporate Governance and Finance Department.
Why is my first loan amount so small?
Most apps, including Blue Peso, start new users with a “Trial Loan” of PHP 2,000 to PHP 3,000.
As you pay on time, your internal credit score increases, allowing for higher limits in the future.
How long does the disbursement take?
Once approved, the funds are usually sent to your e-wallet within minutes.
However, bank transfers might take up to 24 hours depending on the bank’s processing window and holidays.
Final Verdict: Is Blue Peso the Right Choice?
Choosing the Blue Peso loan app is a decision that depends on your immediate financial urgency and your ability to pay.
Because they are backed by Copperstone Lending Inc., they offer a level of legal security that many other apps lack.
The extended term of up to 180 days is a major advantage for those who need more time to manage their cash flow.
However, the reports of Blue Peso complaints regarding collection means you must stay disciplined with your payments.
Only borrow what you need and ensure you are dealing with the official platform to protect your identity and finances.
⚠️ Financial Disclosure: This app is reviewed for informational purposes. Before applying, always verify its SEC Registration and Certificate of Authority. Be mindful of the Effective Interest Rate (EIR), Processing fees, and Service fees. Borrow responsibly to avoid high penalties and debt traps.


Is this Blue Peso app really linked with Copperstone Lending? I want to make sure I am dealing with the correct legal entity before I upload my UMID and selfie.
Hello Mateo! Yes, Blue Peso is the official product of Copperstone Lending Inc. as registered with the SEC. Always double-check the Certificate of Authority number inside the app to ensure you are using the authentic version.
I am planning to apply for a small amount to cover my bills. How does the renewal work for this app if I pay everything on time for the first cycle?
For most borrowers, a successful first repayment often unlocks a higher credit limit and a faster “Re-loan” button. Just maintain a good payment record to enjoy better terms and avoid any collection calls or late fees.