Finn loan app review seekers often ask: Is this platform safe for Filipino borrowers in 2026, or is it another predatory lending trap? With the rise of online credit, distinguishing between a legal loan app and “Shark” lenders is crucial for your financial safety.
This guide provides an in-depth look at Finn, its SEC status, user complaints on Reddit, and how to avoid harassment.
Is Finn Loan App Legit? SEC Registration Details
The most critical question for any borrower in the Philippines is the legal status of the lender.
Finn is not a typical high-interest payday loan. It is a financial wellness platform, often integrated with employers, but it also offers individual services. It is operated by Asiasource Financial Inc. * Company Name: Asiasource Financial Inc.
-
SEC Registration Number: CS201412567
-
Certificate of Authority (CA) Number: 1085
As a sec registered loan app, Finn adheres to the regulations set by the Securities and Exchange Commission of the Philippines. This means they are legally mandated to follow fair debt collection practices and transparent interest rate disclosures.
Finn Loan App Review Philippines: Features & Ratings
Finn positions itself as an “Early Wage Access” (EWA) and salary loan provider. Unlike apps that charge 20-30% interest for 7 days, Finn is significantly more consumer-friendly.
Overall Rating: 8.5/10
-
Legitimacy: 10/10 (Fully SEC regulated)
-
Interest Rates: 9/10 (Very competitive for EWA)
-
User Interface: 8/10 (Modern and easy to navigate)
-
Customer Support: 7/10 (Response times can vary)
Quick Comparison Table
| Feature | Details |
| Loan Amount | ₱2,000 to ₱50,000 (Subject to profile) |
| Interest Rate | 0% to 3% monthly (Varies by product) |
| Repayment Term | 3 to 12 months |
| Processing Time | 24 to 48 hours |
| Requirement | Valid ID, Proof of Income, Active Mobile Number |
Finn Loan App Download Latest Version APK
To ensure security, avoid downloading APK files from third-party websites which may contain malware. Always use official sources:
-
Google Play Store: Search for “Finn – Financial Wellness.”
-
Official Website: Visit the Finn website to get the direct link.
-
Requirements for Installation: Android 6.0 or higher, 50MB free space, and camera permissions for identity verification (e-KYC).
Common Finn Loan Review Complaints & Reddit Discussions
While Finn is a sec registered lending company, no app is without its flaws. We analyzed various Finn loan app review Philippines Reddit threads and Facebook community groups to summarize the common feedback.
1. Verification Delays
Some users report that the “Reviewing” status takes longer than the advertised 24 hours. This usually happens if the uploaded documents (like the Payslip or UMID) are blurred or expired.
2. Loan Amount Limits
New users often complain that their initial credit limit is low (around ₱2,000). Finn increases this limit over time as you build a history of on-time payments.
3. App Glitches
Occasionally, the Finn loan app download latest version APK may experience sync issues with bank accounts (InstaPay/PESONet). Clearing the cache or reinstalling the app usually fixes this.
Dealing with Finn Loan Harassment: Is it a Concern?
One of the biggest fears in the Philippines is “Online Lending Harassment”—where collectors call your contacts or shame you on social media.
Does Finn engage in harassment?
Based on our research and the Finn loan review complaints database, Finn does not follow the aggressive “OLA” (Online Lending App) harassment tactics. Because they are a legitimate sec registered online lending app, they follow the National Privacy Commission (NPC) guidelines.
If you encounter any unprofessional behavior, you should:
-
Record the conversation: Keep screenshots and call logs.
-
Contact Finn Support: Use their official contact number or email.
-
File a Report: If unresolved, escalate to the SEC or the NPC.
How to Apply: A Step-by-Step Guide
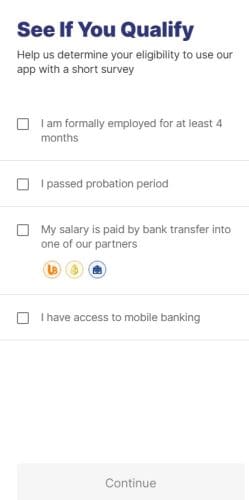
To get approved quickly, follow these steps:
-
Download: Get the app from the Play Store.
-
Register: Use a working Philippine mobile number.
-
Submit IDs: Use a Primary ID (Passport, UMID, Driver’s License, or PhilID).
-
Income Proof: Upload your most recent one-month payslip.
-
Wait for Approval: Check the app status after 24 hours.
Loan Calculation Example
If you borrow a salary advance through Finn, the costs are straightforward.
Example Calculation:
-
Principal: ₱10,000
-
Service Fee (Fixed): ₱300
-
Monthly Interest (e.g., 2%): ₱200
-
Total Repayment (1 Month): ₱10,000 + ₱300 + ₱200 = ₱10,500
Note: Always check the specific disclosure statement within the app before clicking “Accept.”
Frequently Asked Questions (FAQ)
Is Finn Loan App SEC Registered?
Yes, Finn is operated by Asiasource Financial Inc., which is a fully licensed and sec registered loan app in the Philippines. Their CA number is 1085.
What is the Finn Loan contact number?
You can reach their customer service via the in-app chat or through their official social media pages. They typically respond during business hours (9 AM – 6 PM, Monday to Friday).
Can I apply if I am unemployed?
Generally, no. Finn is a financial wellness tool designed for employees and individuals with a steady stream of income. You will need to provide proof of employment to pass the credit scoring.
What happens if I default on my Finn loan?
Late payments will result in penalty fees and a negative impact on your credit score with the Credit Information Corporation (CIC). However, as a legal entity, they do not use illegal harassment tactics.
Final Verdict
Finn is a breath of fresh air in a market saturated with predatory apps. It is a legal loan app that focuses on helping Filipinos manage their cash flow rather than trapping them in debt. If you are looking for a reliable platform and want to see more options, you can check the sec registered loan app list Philippines 2026 to compare Finn with other top-tier providers.
Next Step: Ensure your mobile number is linked to a Gcash or Maya account for faster disbursement after your Finn loan is approved.
⚠️ Financial Disclosure: This app is reviewed for informational purposes. Before applying, always verify its SEC Registration and Certificate of Authority. Be mindful of the Effective Interest Rate (EIR), Processing fees, and Service fees. Borrow responsibly to avoid high penalties and debt traps.


I recently experienced using Finn for an emergency repair. Unlike other apps, the interest was very low, but the verification took almost 3 days! I was worried at first, but it eventually came through. Is this delay normal for first-time users or just a glitch in the [hienthinam] version?
Thanks for sharing your experience, Maria! For first-time users, Finn conducts a thorough manual check of your SEC requirements and payslips, which can take 48-72 hours. Once your profile is established, subsequent “Early Wage Access” requests are usually much faster.
Is Finn really a legal loan app? I checked the SEC website but I want to be 100% sure before I upload my UMID and payslip. I’ve read so many horror stories about harassment from other apps in Reddit groups. Please confirm if they are truly safe for us.
I totally understand your caution! Yes, Finn (Asiasource Financial Inc.) is a legitimate sec registered online lending app with CA No. 1085. They follow strict NPC privacy rules, so your data is much safer here compared to those unregistered “shark” apps you see on social media.
I tried the Finn loan app download latest version APK from a link on Facebook, but my phone flagged it as a threat. Should I be worried? I really need to borrow ₱5,000 for my tuition balance this week. How can I get the official and safest version?
High alert, Bianca! Never download APKs from Facebook links as they often contain malware. Always use the official Google Play Store or the link provided in my review. Staying with the official version ensures you are protected by SEC regulations and app security updates.
Can I apply if I only have a TIN ID? I saw some Finn loan review complaints saying they got rejected even with a job. I really need a loan but I don’t have a UMID or Passport yet. Does Finn accept secondary IDs or are they very strict?
Hi Elena! Based on current requirements, Finn is quite strict and usually requires at least one Primary ID (like UMID, PhilID, or Driver’s License) to match their SEC compliance. A TIN ID might not be enough on its own. I suggest checking our sec registered loan app list for apps with more flexible ID requirements.
I’ve used Finn twice now. I experienced a very smooth process the second time around. My limit increased from ₱2,500 to ₱6,000 automatically. It’s great for workers like me who need a “salubong” before payday. No harassment calls so far, which is a huge relief compared to my past experiences.
That is great to hear, Ricardo! Your experience highlights the “Financial Wellness” aspect of Finn. By paying on time, you’ve built trust, which is why your limit increased. It’s a perfect example of how using a sec registered lending company benefits the borrower in the long run.