Kviku loan review is the most searched topic for Filipinos looking for quick cash solutions, but the burning question remains: Is it a safe, legal loan app, or just another platform that leads to debt harassment?
With the rise of digital lending in the Philippines, distinguishing between a legitimate financial partner and a predatory lender is crucial for your financial safety.
Is Kviku Legit? SEC Registration Status 2026
When asking “Is Kviku legit?”, the first place to look is the Securities and Exchange Commission (SEC). Kviku operates under Kviku Lending Co. Inc., which is a duly recognized entity.
According to official records, Kviku Lending Co. Inc. holds SEC Registration No. CS201918441 and Certificate of Authority (CA) No. 3169. This means they are legally allowed to operate as a lending company in the Philippines.
However, being registered does not always mean a smooth user experience. While it is an sec registered lending company, users must still be wary of the terms and conditions hidden in the fine print.
Quick Summary: Kviku Loan Features at a Glance
| Feature | Details & Specifications |
| Official App Name | Kviku – Online Loan Philippines |
| Legal Entity | Kviku Lending Co. Inc. |
| SEC Registration No. | CS201918441 |
| Certificate of Authority | No. 3169 |
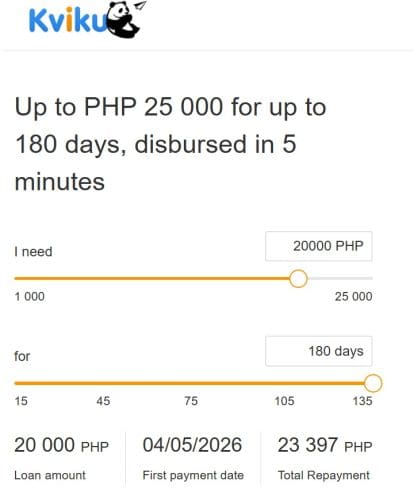
| Loan Amount | ₱1,000 – ₱25,000 (Increases with credit history) |
| Loan Tenure | 60 days to 180 days |
| Interest Rate | Starting from 0.19% per day |
| Approval Time | As fast as 5 minutes to 24 hours |
| Disbursement | Bank Transfer, GCash, Maya |
| Primary Requirement | 1 Valid Government ID & 20-55 years old |
Kviku Contact Information and Support 2026
-
Website: https://kviku.ph
-
Contact: [email protected]
- Business Address: 18A Trafalgar Plaza, 105 H.V. Dela Costa Street, Salcedo Village, Makati City, 2026 Philippines.
Kviku Loan App Features and Requirements
The Kviku loan app is popular due to its fully digital application process. You don’t need to visit a physical branch or provide collateral.
Loan Amount and Terms
Initially, first-time borrowers may only be approved for a small amount, typically ranging from PHP 1,000 to PHP 5,000. As you build a credit history within the app, the limit can increase up to PHP 25,000.
The repayment period usually spans from 60 days to 180 days, depending on the approved offer.
Kviku Requirements
To apply, you must meet the following Philippine-specific criteria:
-
Filipino Citizenship: Must be a resident of the Philippines.
-
Age: 20 to 55 years old.
-
Valid ID: At least one government-issued ID (UMID, Driver’s License, Passport, or PRC ID).
-
Mobile Number: An active Philippine mobile number.
-
Stable Income: Evidence of employment or a steady source of funds.
How to Apply for a Kviku Loan: Step-by-Step Guide 2026
The application process for the Kviku loan app is designed to be fast and 100% digital, catering to Filipinos who need cash in minutes. Since Kviku is a legal loan app, the process requires real-time identity verification to prevent fraud.
Step 1: Download the Official App
Go to the Google Play Store or Apple App Store and search for “Kviku – Online Loans Philippines.” Ensure you are downloading the app from the official developer, Kviku Lending Co. Inc., to avoid clones.
Step 2: Register with Your Mobile Number
Open the app and enter your active Philippine mobile number. You will receive a One-Time Password (OTP) via SMS to verify your account.
Step 3: Fill Out the Application Form
Provide your basic personal information, including:
-
Full name (matching your ID).
-
Home address and length of stay.
-
Employment details or source of income.
-
Active email address.
Step 4: Identity Verification (KYC)
You will need to take a clear photo of your valid government-issued ID (such as UMID, Passport, or Driver’s License). The app may also require a “selfie” with your ID to confirm your identity.
Step 5: Select Loan Amount and Disbursement Method
Choose how much you want to borrow and where you want to receive the funds. Kviku supports:
-
Bank transfers (all major Philippine banks).
-
E-wallets like GCash or Maya.
Step 6: Wait for Approval and Disbursement
The Kviku lending app uses an automated scoring system. Approval often takes less than 3 minutes. Once approved, you must electronically sign the loan contract, and the money will be sent to your chosen account shortly.
Tips for a Higher Approval Rate
-
Double-check your ID: Ensure the photo is not blurry and no information is covered.
-
Stable Internet: Use a strong connection to prevent the app from timing out during the KYC process.
-
Accuracy: Mismatched names between your ID and bank account can lead to automatic rejection and increase Kviku review complaints.
-
Be Honest: Even if you are self-employed, providing accurate income details increases your trustworthiness in their credit scoring system.
Understanding the Kviku Loan Interest Rate
One of the biggest Kviku complaints involves the cost of borrowing. While the app advertises low rates, the cumulative cost can be high when including service fees.
| Loan Component | Details |
| Daily Interest Rate | Up to 0.19% per day |
| Annual Percentage Rate (APR) | Can exceed 60% depending on the term |
| Processing Fee | Varies based on loan amount |
| Late Payment Penalty | Significant daily charges for overdue accounts |
Simple Interest Calculation Example:
If you borrow PHP 5,000 for 60 days with a daily interest of 0.19%:
-
Interest per day = 5,000 * 0.0019 = PHP 9.50
-
Total Interest for 60 days = 9.50 * 60 = PHP 570
-
Total Repayment = PHP 5,570 (Excluding processing fees)
Note: Always check the “Truth in Lending Act” disclosure statement provided in the app before accepting the loan.
Kviku Harassment Review: Addressing the Concerns
Search for Kviku harassment review on social media, and you will find a mix of experiences. While Kviku is a legal entity, many users have reported aggressive collection tactics.
Common Kviku Complaints
-
Contacting References: Users have reported that collectors call their emergency contacts or even Facebook friends when a payment is delayed.
-
Aggressive Language: Some Kviku review complaints on Reddit mention receiving threatening SMS or calls from collection agents.
-
High Penalties: The rapid accumulation of late fees often makes it impossible for borrowers to “catch up” once they miss a single payment.
The National Privacy Commission (NPC) and the SEC have strict guidelines against “Unfair Debt Collection Practices.” If you experience “public shaming” or unauthorized access to your phone’s contact list, you have the right to file a formal complaint.
How to Report Kviku to SEC and NPC? 2026
If you believe you are a victim of unfair debt collection or privacy violations, you should not stay silent. While Kviku is an sec registered online lending app, they are strictly bound by Philippine laws, specifically SEC Memorandum Circular No. 18 (Series of 2019) and the Data Privacy Act of 2012.
Filing a Complaint with the SEC
The Securities and Exchange Commission (SEC) oversees the conduct of lending companies. If you experience “debt shaming,” threats, or profane language, follow these steps:
-
Gather Evidence: Take screenshots of threatening SMS, call logs, or social media posts made by collectors.
-
Download the Form: Visit the SEC official website and look for the Lending/Financing Company Complaint Form.
-
Submit via Email: Send your notarized complaint-affidavit along with your evidence to the Enforcement and Investor Protection Department (EIPD) at [email protected] or [email protected].
-
Visit the SEC iMessage Portal: You can also file a ticket directly through their online portal at
imessage.sec.gov.ph.
Filing a Complaint with the NPC (National Privacy Commission)
If the Kviku loan app accessed your contact list without explicit consent or messaged people not listed as character references, this is a severe data privacy breach.
-
Submit a Sworn Complaint: Download the NPC Complaint Form from
privacy.gov.ph. -
Detail the Breach: Explain how your data was misused (e.g., “The app messaged my Facebook friends who are not part of the loan agreement”).
-
Send to NPC: Email the scanned, notarized form to [email protected].
-
Coordinate with Authorities: The NPC has the power to issue “Cease and Desist” orders against apps that violate Filipino privacy rights.
Pro Tip: When reporting, always mention that you are dealing with a legal loan app registered under Kviku Lending Co. Inc. to help the authorities identify the specific entity in their records.
Pros and Cons of Using Kviku Lending App
Pros:
-
Fast Approval: Loans are often processed within 24 hours.
-
Convenience: Entirely paperless and mobile-based.
-
Disbursement: Funds are sent directly to your bank account or G-Cash/Maya.
Cons:
-
Expensive: High interest compared to traditional bank loans.
-
Collection Tactics: Known for persistent and sometimes intrusive collection calls.
-
Data Access: Requires permissions to access various phone functions.
Frequently Asked Questions (FAQs)
Is Kviku SEC Registered?
Yes, Kviku is an sec registered online lending app operated by Kviku Lending Co. Inc. You can verify their status on the official SEC Philippines website under the list of “Lending Companies with Certificate of Authority.”
How to pay Kviku loans in the Philippines?
You can pay through several channels, including:
-
7-Eleven (via CLIQQ kiosk)
-
GCash or Maya (Pay Bills section)
-
Bayad Center
-
Bank Transfer
What happens if I don’t pay my Kviku loan?
If you default, you will face heavy late fees, and your credit score will be negatively affected. Furthermore, you may experience persistent collection efforts, which are frequently cited in Kviku complaints.
Is Kviku safe to use?
Technically, it is safe because it is a regulated entity. However, from a financial and privacy standpoint, you should only use it as a last resort due to the high interest and potential for aggressive collection if you fail to pay on time.
Where can I find honest Kviku reviews?
For unfiltered feedback, Reddit (specifically r/utangPH) is an excellent resource where Filipinos share their real-life experiences with debt collectors and the app’s overall reliability.
Expert Advice for Borrowers in 2026
Before downloading any lending app, always perform your due diligence. Kviku is a legitimate company, but it is not a “cheap” loan. It is designed for short-term emergencies, not long-term financial management.
If you find yourself being harassed, document every call and text message. You can report these violations to the SEC Enforcement and Investor Protection Department or the National Privacy Commission.
Remember, no legitimate lender is allowed to threaten you with physical harm or use profane language to collect a debt. Stay informed, read the terms, and only borrow what you can afford to repay.
⚠️ Financial Disclosure: This app is reviewed for informational purposes. Before applying, always verify its SEC Registration and Certificate of Authority. Be mindful of the Effective Interest Rate (EIR), Processing fees, and Service fees. Borrow responsibly to avoid high penalties and debt traps.


I experienced a very fast approval with Kviku last week, but the interest was higher than I expected. Does the interest rate decrease if I pay early, or is it fixed once the loan is approved? I want to make sure I don’t pay more than necessary.
Thank you for sharing your experience, Juan! Typically, interest is fixed based on the contract, but some apps offer rebates for early settlement. I recommend checking the “Truth in Lending” statement in your app to see if they waive a portion of the daily interest for early payments.
I’m worried about the Kviku harassment review reports I see on Reddit. They say the app accesses your phone contacts. If I don’t give permission to my contacts, will they still approve my loan? I need the cash but I also value my privacy and my friends’ safety.
Hi Maria! Most online lending apps, including Kviku, require contact access as part of their credit scoring. If you deny permissions, there is a high chance the app will automatically reject your application. Privacy is a major concern, so please weigh the risks before proceeding.
I had a bad experience with their collection agent. I was only one day late due to a bank system glitch, and they already started calling my secondary reference. It was very embarrassing. Is this even legal under the SEC rules? I felt so harassed during that phone call.
Sorry to hear about that, Angelo. Under SEC Memorandum Circular No. 18, contacting people not listed as references or using shaming tactics is prohibited. You can document these calls and file a formal complaint with the SEC or the National Privacy Commission to protect your rights.